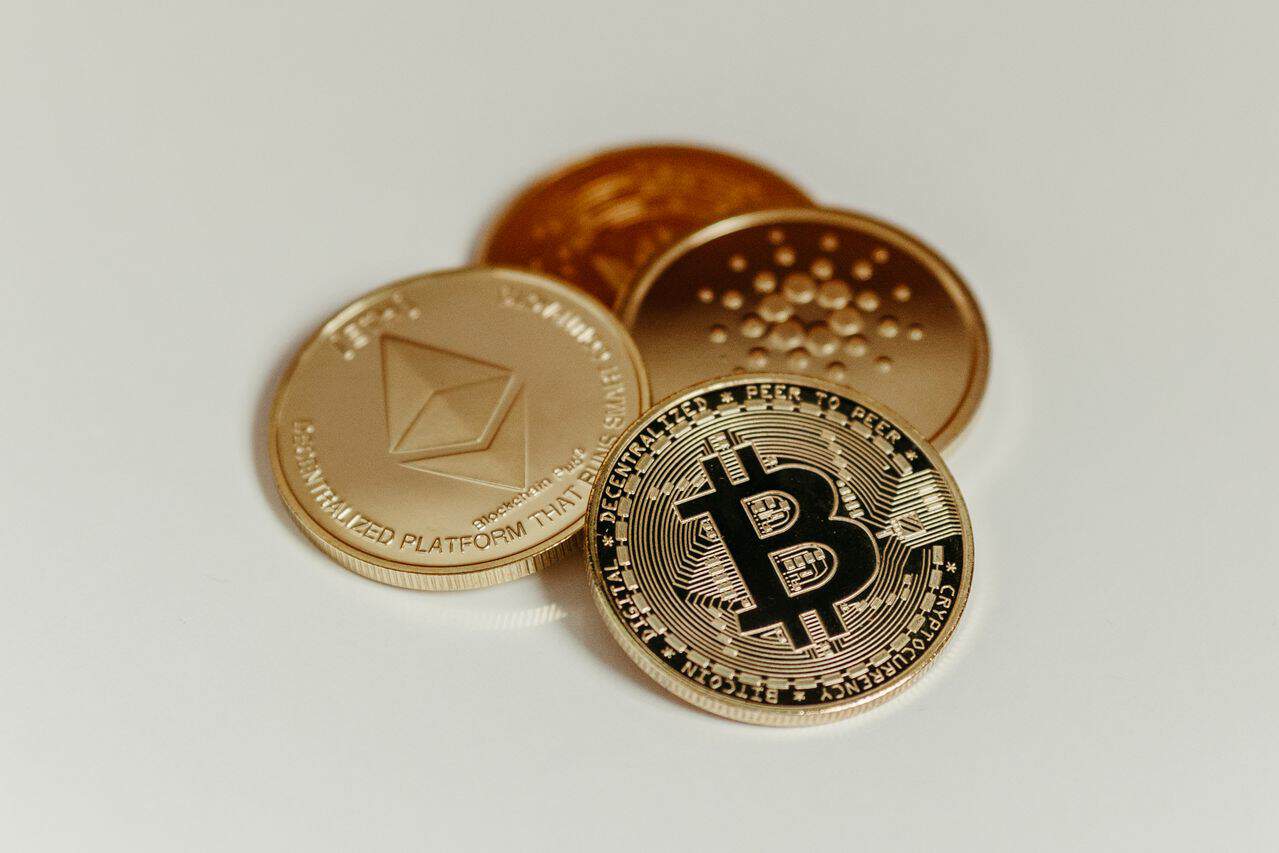

Accepting payment in Bitcoin, Ethereum, USDT or another digital currency in the UAE does not remove the need to determine the transaction’s value in UAE dirhams for VAT purposes.
The Federal Tax Authority has now prescribed exactly how that conversion should be carried out.
Under Directive on Tax Transactions No. 3 of 2026 for Value Added Tax, Taxable Persons who supply digital currency or receive digital currency as consideration for goods or services must use a standardised methodology when translating that value into AED for their VAT returns.
The Directive introduces consistency into an area where businesses may previously have relied on different exchange rates, platforms or internal valuation methods.
The key principle is simple:
A crypto payment may be received in digital currency, but the VAT return still needs an AED value calculated using the FTA’s prescribed methodology.
Why the New Directive Matters
Digital currencies can fluctuate rapidly.
The value of the same crypto asset may differ:
- between trading platforms;
- from minute to minute;
- between the time an invoice is issued and payment is received; and
- between the time a business receives the asset and later converts it into AED.
That creates an obvious tax problem.
If every business could choose whichever exchange or rate it preferred for each transaction, the AED value reported for VAT purposes could vary materially even where the underlying crypto payment was identical.
Directive No. 3 of 2026 addresses that problem by introducing a repeatable and auditable conversion method.
Who Does the Directive Apply To?
The Directive applies to a Taxable Person in either of two broad situations.
First, where the Taxable Person makes a supply of digital currency.
Second, where the Taxable Person supplies goods or services and receives the consideration in digital currency.
That means the rules are relevant not only to businesses operating directly in digital assets.
They can also affect an ordinary UAE business that simply accepts cryptocurrency as payment.
For example, the framework may become relevant to a business accepting digital currency for:
- professional services;
- consultancy;
- technology services;
- retail purchases;
- hospitality;
- property-related services;
- subscriptions; or
- other taxable transactions.
The payment method does not remove the need to account for VAT correctly.
Three Approved Exchange Platforms Must Be Selected
The starting point is platform selection.
The Taxable Person must choose three centralised public digital-currency exchange platforms from the list approved and published by the Federal Tax Authority.
Those three platforms then become the reference points used for the business’s relevant digital-currency transactions.
The important point is consistency.
A business cannot simply choose one exchange for one transaction and another exchange for the next depending on which produces the most favourable AED value.
The Same Three Platforms Must Be Used for the Calendar Year
Once selected, the same three platforms must be used for all relevant transactions undertaken during the same calendar year.
That is particularly important for finance teams because the rule is calendar-year based rather than linked to the business’s own financial year or an arbitrary rolling 12-month period.
A business should therefore formally document which three approved platforms it has selected and ensure those platforms are consistently used by:
- finance;
- tax;
- accounting;
- treasury; and
- any outsourced bookkeeping provider.
Using different sets of exchanges within the same year could undermine consistency in VAT reporting.
How Is the AED Value Calculated?
For each relevant transaction, the business must obtain the exchange rate for the digital currency from each of its three selected platforms.
It must then calculate the arithmetic average of those three rates.
That average rate is used to convert the value of the digital currency into UAE dirhams.
The approach can be illustrated simply.
Suppose a business receives payment in a digital currency and its three selected platforms show AED-equivalent rates of:
- AED 100;
- AED 102; and
- AED 101.
The arithmetic average would be AED 101.
That average, rather than any single platform’s rate, becomes the basis of the AED conversion for VAT reporting.
The Date and Time Matter
Digital assets can be volatile.
A rate taken in the morning may differ materially from the rate available later the same day.
The Directive therefore requires the business to use the rates prevailing at the relevant date and time.
Depending on the transaction, that may be the date and time of:
- the supply; or
- receipt of the consideration,
as applicable under the VAT rules.
This creates an important operational requirement.
A business cannot simply take the end-of-day price or a monthly average unless that happens to correspond with the legally relevant valuation point.
The timestamp matters.
Why This Is More Than an Accounting Detail
The valuation determines the AED amount disclosed for VAT purposes.
That figure can affect:
- taxable value;
- output VAT;
- VAT return reporting;
- accounting records;
- input tax allocation in certain circumstances; and
- the audit trail available to the FTA.
An apparently minor difference in the exchange rate can become significant where a business processes a high volume or high value of digital-currency transactions.
The conversion methodology therefore needs to be embedded within the tax process rather than left to informal judgment at the end of the VAT period.
The Directive Does Not Create a New VAT Rate
Another important distinction is that the Directive does not introduce a new VAT rate for crypto payments.
The UAE’s ordinary VAT rules continue to determine whether the underlying supply is:
- taxable;
- zero-rated;
- exempt; or
- otherwise treated under the VAT legislation.
The Directive addresses valuation.
It determines how the value of the digital currency is translated into AED for reporting purposes.
A business should therefore separate two questions:
- What is the VAT treatment of the underlying supply?
- How do we determine the AED value of the digital-currency amount involved?
The Directive answers the second question.
Receiving Crypto Does Not Necessarily Change the VAT Treatment of the Supply
Suppose a UAE business sells a taxable service and receives payment in digital currency instead of AED.
The fact that the customer pays in crypto does not, by itself, transform the nature of the service.
The business must still analyse the service under the ordinary VAT rules.
The digital currency simply creates an additional valuation step.
This is an important point because “crypto tax” is sometimes discussed as though digital currency creates an entirely separate tax system.
In many commercial situations, it does not.
The tax treatment of the underlying transaction may remain conventional even though the payment method is not.
What If the Crypto Is Converted Into AED Later?
This is another practical issue.
A business may receive digital currency today but convert it into dirhams several days later.
The AED amount eventually realised on conversion may therefore differ from the value used for VAT reporting.
That difference does not mean the VAT return should simply be revised to match the later cash proceeds.
For VAT purposes, the relevant valuation must be made at the date and time prescribed under the Directive and the broader VAT framework.
A later gain or loss caused by movement in the digital currency’s value is a separate accounting and potentially tax matter.
Businesses should therefore avoid confusing:
- the AED value used for VAT at the relevant transaction point; and
- the AED amount eventually realised when the crypto asset is sold or converted.
Stablecoins Still Require Proper Conversion
The rules are also relevant to digital currencies designed to track the value of traditional currencies.
A stablecoin may be intended to remain close to a fixed value, but that does not necessarily remove the need to follow the FTA’s prescribed methodology.
Market prices can differ slightly between exchanges.
The fact that a digital asset is commonly treated as “stable” should not lead a business to bypass the required conversion process.
The business should still determine the AED value in accordance with the Directive where it applies.
Businesses Must Retain Evidence of the Rates Used
The FTA requires supporting records.
Taxable Persons must retain evidence of the exchange rates obtained from each of the three selected platforms, in addition to their ordinary VAT record-keeping obligations.
That documentation is important because digital-currency prices change continuously.
If the FTA reviews a transaction months or years later, the business should be able to demonstrate:
- which platforms were selected;
- what rate each platform showed;
- the relevant date and time;
- how the average was calculated; and
- the AED amount ultimately reported.
A spreadsheet showing only the final AED figure may not be enough if the underlying rates cannot be reconstructed.
Businesses Should Build a Repeatable Process
For occasional crypto payments, it may be possible to carry out the conversion manually.
For higher volumes, manual processing becomes increasingly risky.
Businesses accepting digital currency regularly should consider implementing a structured process that:
- records the transaction timestamp;
- captures rates from the three selected platforms;
- calculates the average automatically;
- stores the supporting evidence;
- links the calculation to the relevant invoice or transaction;
- records the AED amount used for VAT; and
- preserves the data for audit purposes.
The objective is consistency.
The same transaction should produce the same tax result regardless of which employee processes it.
What If a Rate Is Not Available on Three Platforms?
This is a particularly important edge case.
Some digital currencies may not be traded on all of the FTA-approved platforms.
The Authority has indicated that further guidance will address the procedure to be followed where an exchange rate is not available from three listed platforms.
Businesses dealing in less liquid or less widely traded digital assets should therefore take particular care.
They should not simply improvise their own methodology where the prescribed three-platform data cannot be obtained.
Where the required rates are unavailable, the business should review the applicable FTA clarification or obtain appropriate tax advice before reporting the transaction.
What Finance Teams Should Do Now
Businesses accepting digital currency should review their VAT procedures rather than waiting until the next filing deadline.
A practical compliance exercise should include:
1. Identify whether the business receives or supplies digital currency
Map all transactions involving crypto or other digital currencies.
2. Select three approved platforms
Formally choose the three FTA-approved exchanges that will be used during the calendar year.
3. Document the selection
Record the chosen platforms internally and communicate the decision to relevant finance and tax personnel.
4. Capture the correct timestamp
Ensure systems record the date and time relevant to the transaction.
5. Calculate the arithmetic average
Use the three platform rates rather than selecting a single exchange rate.
6. Preserve evidence
Retain the rates and supporting records used for each conversion.
7. Align accounting and VAT systems
Ensure the AED valuation used in the VAT return can be reconciled with the underlying transaction records.
8. Separate later crypto gains or losses
Do not confuse later changes in the asset’s value with the AED amount required for the original VAT reporting.
Why Consistency Matters
The real significance of Directive No. 3 of 2026 is standardisation.
Digital currencies operate across multiple trading venues with continuously changing prices.
Tax administration, by contrast, requires transactions to be recorded in a consistent monetary value.
The Directive creates a bridge between those two realities.
By requiring:
- three approved platforms;
- a numerical average;
- a precise date and time;
- consistent use throughout the calendar year; and
- supporting records,
the FTA has created a methodology that can be reviewed and reproduced during an audit.
That is considerably more robust than allowing taxpayers to select whichever market price appears reasonable at the time.
A Wider Sign of Crypto Becoming Part of Ordinary Business Compliance
The Directive is also significant beyond its technical VAT function.
It reflects the increasing integration of digital assets into ordinary UAE commercial activity.
As businesses begin accepting cryptocurrency alongside traditional payment methods, regulators and tax authorities need rules capable of dealing with those transactions without treating them as entirely separate from the existing tax system.
This is what the Directive achieves.
It does not reinvent VAT for crypto.
It provides a practical method for fitting digital-currency transactions into the existing VAT framework.
Conclusion
The UAE has now given businesses a clear methodology for converting digital-currency transactions into dirhams for VAT reporting.
Under Directive on Tax Transactions No. 3 of 2026, affected Taxable Persons must select three approved centralised public exchange platforms, use the same three throughout the calendar year and calculate the arithmetic average of the relevant rates at the appropriate date and time.
They must also retain evidence supporting those rates.
For businesses accepting crypto, the practical lesson is straightforward:
The digital currency may fluctuate, but the VAT reporting methodology cannot.
Businesses should establish a consistent conversion and record-keeping process now so that every relevant transaction can be traced from the original digital-currency amount to the AED figure ultimately reported to the Federal Tax Authority.
Al Kabban & Associates
For businesses seeking guidance, Al Kabban & Associates, with over 30 years of experience in UAE law and recognition by Legal 500, stands ready to help corporations build resilience against legal risks while ensuring compliance with local and international standards. For more information or to schedule a consultation, contact us at +971 4 453 9090 or visit www.alkabban.com. You can also follow us on social media for more updates on everything law related in the UAE: @Alkabban_Law
ALSO READ –